Term Loans for Business: One Product. Dozens of Ways to Use It. Here’s How.
| AI OVERVIEWTerm loans for business give owners a lump sum upfront and a fixed payback plan. Owners use the cash for equipment, hiring, stock, new locations, marketing, and debt cleanup. Most lenders want one year in business, a 550+ FICO, and $100K in yearly revenue. Simply Capital Source can fund approved owners in as little as 24 hours. |
| TL;DRTerm loans for business pay out one lump sum, repaid in fixed amounts.Use one for growth, cash flow, or cleaning up pricey debt.It works best when your goal has a clear price tag.Working capital loans for small business suit short, fast needs.Simply Capital Source can fund you in as little as 24 hours. |
Your bank said, “Come back in three months.” Your rival just bought the machine you wanted. Term loans for business close that gap fast. They hand you a lump sum today and let you repay it in fixed payments.
No guessing. No surprise bills.
Here’s what most owners miss. This one product has dozens of uses. Not just equipment. Not just rent. Dozens. This guide shows you where the money can go, what it costs, and how to get approved without the usual bank runaround.
What Are Term Loans for Business, Really?
Think of it as a deal with three parts. You borrow a set amount. You repay it over a set time. You pay a set rate. That’s it.
Terms usually run from one to ten years. Shorter terms mean bigger payments but less total interest. Longer terms ease monthly pressure but cost more overall.
Unlike a credit line, you get all the money at once. That makes term loans for business perfect for one-time, high-cost goals.
12 Smart Ways to Use Term Loans for Business
Pick the bucket that matches your goal.
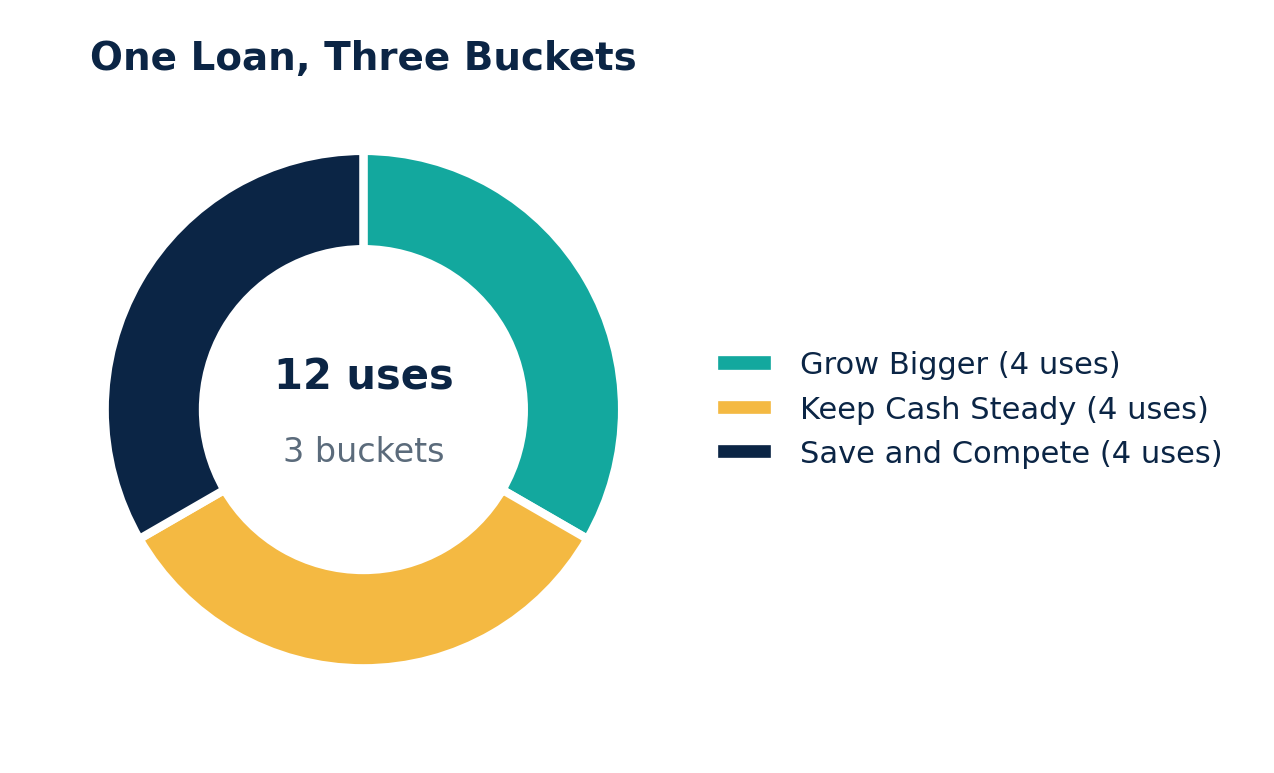
Grow Bigger
| 1 | Buy equipment | New ovens, trucks, or machines pay for themselves faster than you’d think. |
| 2 | Open a new location | Cover the lease, buildout, and first-month costs. |
| 3 | Hire your team | Pay recruiting costs and early salaries before sales catch up. |
| 4 | Launch a new product line | Fund design, testing, and the first big batch. |
Keep Cash Steady
| 5 | Stock up on inventory | Buy in bulk before busy season and lock in better prices. |
| 6 | Smooth seasonal dips | Cover payroll and rent during slow months. |
| 7 | Cover surprise costs | A broken freezer shouldn’t freeze your growth. |
| 8 | Bridge slow-paying clients | Keep the lights on while invoices sit unpaid. |
Save and Compete
| 9 | Refinance pricey debt | Swap high-rate balances for one fixed payment. |
| 10 | Run a marketing push | Ads, a new website, and launch events all count. |
| 11 | Upgrade your tech | Point-of-sale systems, software, and security tools cut daily friction. |
| 12 | Buy out a partner or rival | Take control or grab market share. |
Twelve uses. One loan. Your call.
Where Does the Money Pay Off Fastest?
Not every dollar works at the same speed. Here’s a quick guide.
| Use | Payoff Speed | Best For |
|---|---|---|
| Equipment | Medium | Contractors, restaurants, factories |
| Inventory | Fast | Retail, e-commerce |
| Refinancing | Immediate savings | Owners with high-rate debt |
| New location | Slow | Brands with proven demand |
| Marketing | Fast to medium | Service businesses |
Term Loans for Business vs. Other Funding: A Quick Face-Off
Choosing the wrong product costs money. Compare before you sign.
| Feature | Term Loan | Working Capital Loan | SBA Loan |
|---|---|---|---|
| Best for | Big, planned goals | Short-term cash gaps | Long-term asset buys |
| Payment style | Fixed, regular | Short, quick payback | Fixed, long-term |
| Speed | As fast as 24 hours | Very fast | Slower |
| Typical cost | Moderate | Higher | Lowest |
Many owners also look at working capital loans for small businesses when the need is short and urgent. Those loans cover rent, payroll, and quick gaps. A term loan covers the big, planned stuff. Some owners use both: working capital loans for small business for the daily grind, and a term loan for the big leap.
Term Loans for Business by Industry: Who Uses What
Every industry has a favorite use. Here’s a peek.
| Industry | Common Use |
|---|---|
| Restaurants | New kitchen gear, second location |
| Trucking | Fleet upgrades, repairs |
| Retail | Seasonal inventory |
| Contractors | Heavy machinery, hiring crews |
| Healthcare | Imaging tools, new clinic space |
A Quick Story: One Loan, Three Wins (Hypothetical)
Picture a bakery owner named Dana. She takes one term loan. Part buys a bigger oven. Part funds a second delivery van. The rest clears a high-rate card balance.
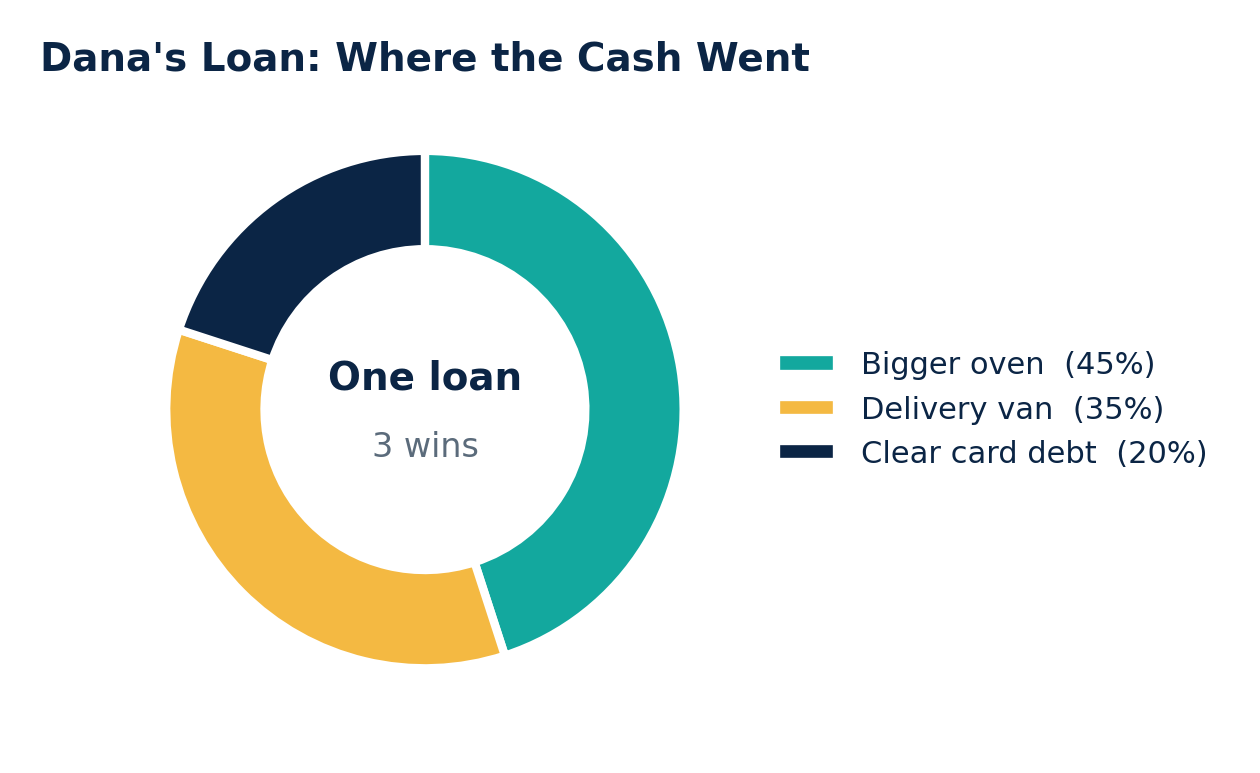
One loan. Three wins.
Baking capacity jumps. Deliveries open a fresh revenue stream. Her monthly debt bill shrinks to one fixed payment instead of three messy ones.
That’s the secret behind term loans for business. They bend to your plan, not the other way around.
The chart is for illustration only. The split shown is a made-up example.
How to Pick Your Best Use in 3 Questions
Still unsure where your money belongs? Ask yourself:
- Will it earn more than it costs? Equipment and stock often do.
- Is the need one-time or ongoing? One-time fits a term loan. Ongoing needs may fit working capital loans for small business.
- Can my cash flow carry the payment? Run the numbers before you apply.
Yes to all three? You’re ready to move.
The Cost Reality Check
A loan’s price tag has three parts: the rate, the fees, and the length. Miss one and you misjudge the deal.
| PRO TIPAsk for the total payback amount in writing. A low monthly payment can hide a high final bill. |
| ANOTHER TIPAsk if early payoff carries a penalty. Paying ahead can save real money. |
Do You Qualify? The 4-Point Check
Most lenders look for the same basics. Simply Capital Source keeps it simple:
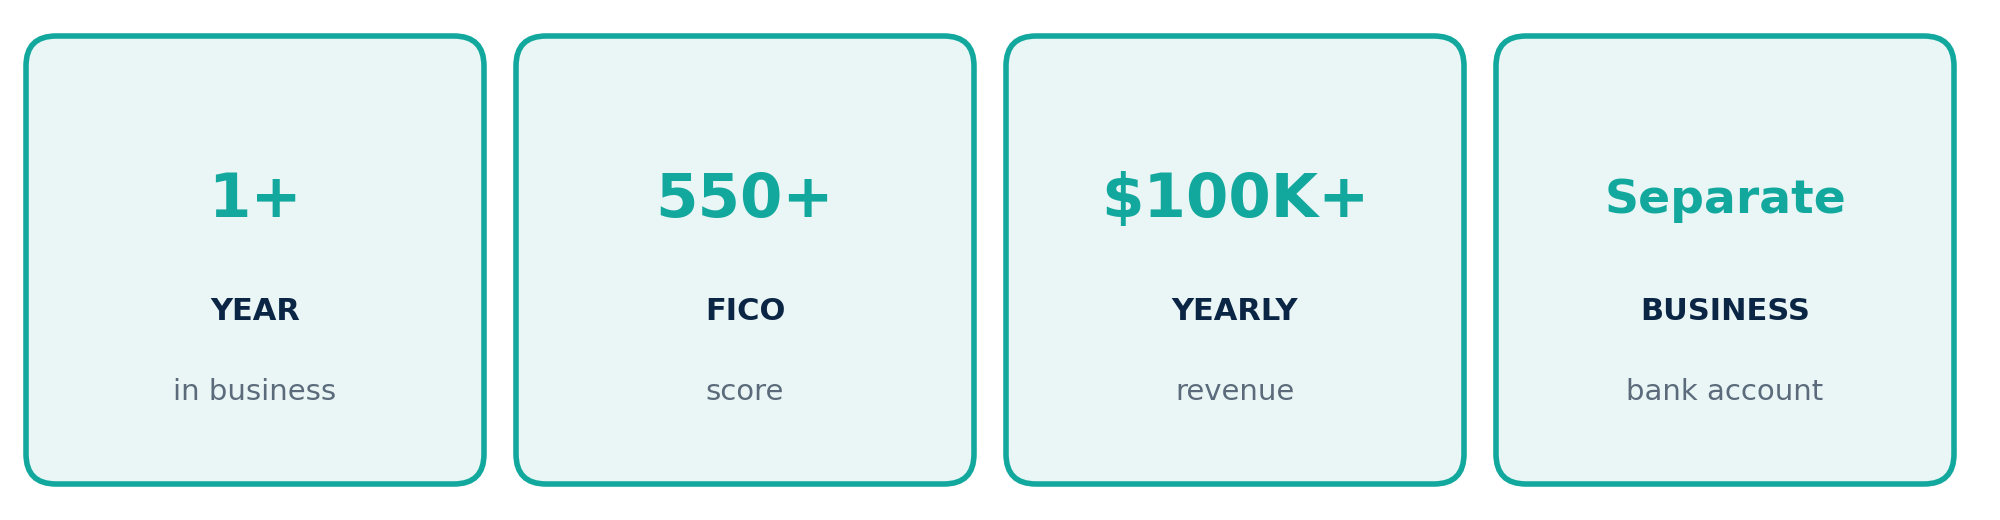
Hit all four? You’re likely in range. Fall short on one? Talk to an advisor anyway. Many owners are surprised by their options.
Approval speed depends on clean records. Have bank statements and your ID ready, and term loans for business can move from application to funding fast. The steps are simple: apply online, review options with an advisor, get funded.
5 Mistakes That Make Term Loans for Business Cost More
- Borrowing too much. Take what the goal needs, not what’s offered.
- Ignoring the total cost. Check the rate, fees, and payback together.
- Picking a term that strains cash. A payment you can’t carry is a trap.
- Skipping the plan. Know the exact job each dollar will do.
- Waiting too long. Delay costs sales. A missed deal doesn’t come back.
Myth vs. Fact
| MYTH | FACT |
| Term loans are only for big companies. | Owners with one year in business and $100K in yearly revenue can qualify. |
| Banks are the only door. | Online funders like Simply Capital Source can move much faster. |
| A loan is always a risky bet. | Fixed payments keep costs predictable, so planning gets easier. |
Why Waiting Costs More Than Borrowing
Every month you wait has a price. A rival grabs the lease. Your best hire signs elsewhere. The supplier discount ends.
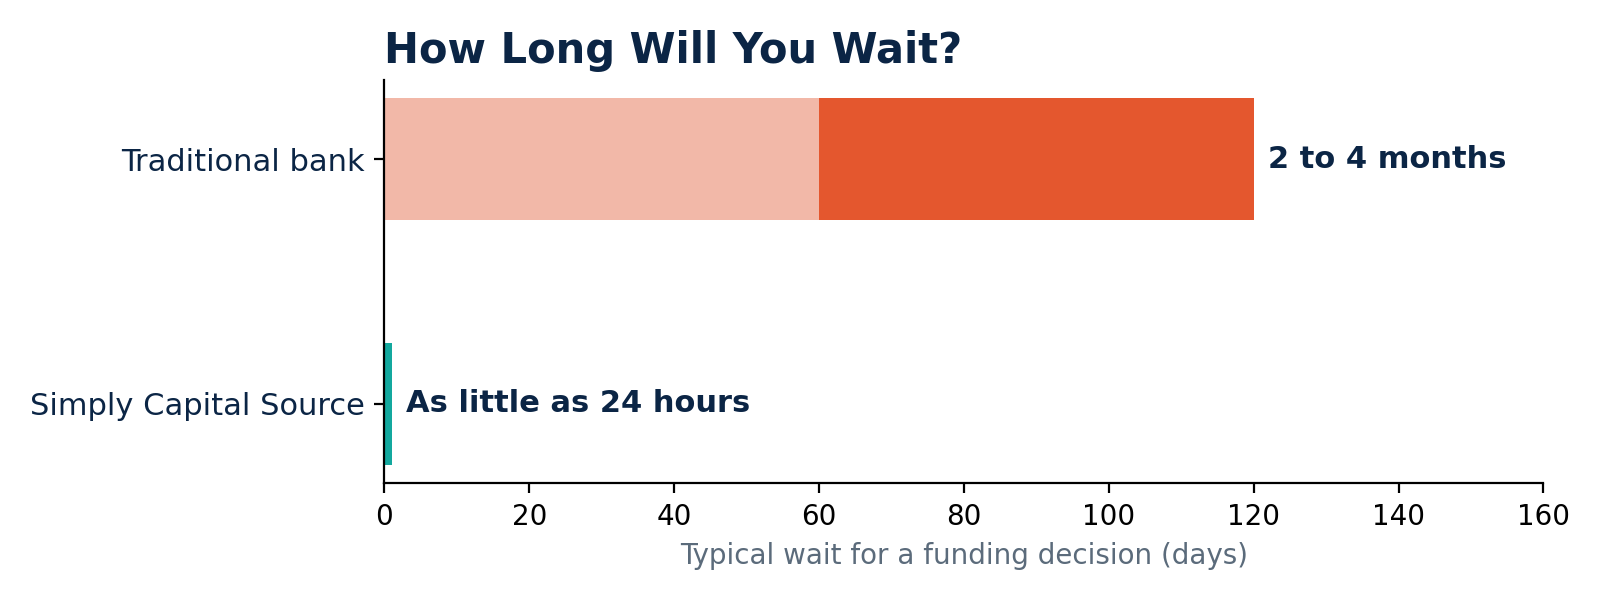
Banks can take two to four months. That’s a full season of missed sales. Simply Capital Source cuts that wait to as little as 24 hours.
Speed isn’t a luxury. It’s a strategy. The owner who moves first usually wins the deal.
Conclusion: Your Move
Term loans for business aren’t just a way to buy equipment. They’re a flexible tool for growth, cash flow, and smarter debt. One loan, dozens of jobs.
The question isn’t whether you need funding. It’s whether you’ll act while the window is open. Every day you delay is a day your rivals pull ahead.
Know your goal. Check your numbers. Then move.
| Ready to Fund Your Next Move With Simply Capital Source?Good deals don’t wait. Neither should you. Simply Capital Source is built for owners across the U.S. who are tired of the bank queue. Funding can arrive in as little as 24 hours.Don’t let another quarter slip by while your rivals grow. Apply today, talk with a funding advisor, and put your capital to work.Apply Today or call (201) 357-0308The best time to move was yesterday. The second best is right now. |
Frequently Asked Questions (FAQs)
| 1. What are term loans for business used for?They cover high, planned costs like equipment, new locations, hiring, inventory, marketing, and debt refinancing. One lump sum, one fixed payment plan. |
| 2. How fast can I get funded?Simply Capital Source can fund approved owners in as little as 24 hours, while banks often take two to four months. |
| 3. Can I qualify with a 550 FICO score?Yes, if you also have one year in business, $100K in yearly revenue, and a separate business bank account. Apply, and an advisor will walk you through your options. |
| 4. Is a term loan better than a line of credit?It depends on the goal. Term loans fit one-time, high-cost needs. Credit lines fit ongoing, small expenses. |
| 5. Will a term loan hurt my cash flow?Not if you plan well. Fixed payments make budgeting easy, so pick a term your monthly revenue can carry. |