TL;DRSeven small lines in your contract can add thousands to what you repay. Check the APR, fees, early-payoff rules, payment schedule, collateral, penalty clauses, and balloon payments. Ten minutes now beats a costly surprise later. |
AI OVERVIEWWhich loan terms matter most before signing a business loan? Seven stand out: APR, fees, prepayment rules, payment schedule, collateral and personal guarantees, default penalties, and balloon payments. Fast funding, such as equipment financing approval in 24 hours, is a real perk. It works best when the loan terms are clear and fair. |
You signed fast. You read the rate. You skipped the other twelve pages. Sound familiar? Most owners do the same, and lenders know it. The loan terms tucked inside those pages decide what you truly pay.
One missed line can mean a surprise fee, a harsh penalty, or a payment that lands on your worst cash day. It happens to sharp people every week.
So here’s your cheat sheet. Seven terms. Plain English. One question for each, so you can speak up before the pen hits paper.
Why Lenders Count on You Skimming
Here’s the uncomfortable truth. Contracts run long, and tired owners just want the cash.
That’s the gap. The loan terms most likely to hurt you often sit in small print, under dull headings. You sign. They stay. Months later, you wonder why the math doesn’t add up.
Picture Luis, a contractor who needed a new truck. He loved the 7% rate and signed in a day. Later, he found a 4% fee and a penalty for early payoff. Same truck. Much pricier deal.
The fix isn’t a law degree. It’s knowing where to look. Reading loan terms is a skill, and you’re about to get it.
The Seven at a Glance
Here’s the map before the tour.
|
# |
Term |
Where It Bites |
Skim Risk |
|---|---|---|---|
|
1 |
APR vs. rate |
Your total cost |
High |
|
2 |
Fees |
The cash you receive |
High |
|
3 |
Prepayment rules |
Paying off early |
Medium |
|
4 |
Payment schedule |
Daily cash flow |
High |
|
5 |
Collateral and guarantees |
What you could lose |
High |
|
6 |
Default and late clauses |
Rough-month penalties |
Medium |
|
7 |
Balloon payments |
The final payment |
Medium |
1. APR: The Rate Behind the Rate
A lender says 8%. Sounds friendly. But the interest rate shows only part of the price. APR adds fees into the math, so it’s the truer number. Two offers can share the same rate and carry very different APRs.
Watch for factor rates, too. A factor rate of 1.2 on $50,000 means you repay $60,000. That’s a flat 20% cost, even if the loan runs only a few months.
ASK THIS: What’s the APR, and what’s my total payback?
2. Fees: The Cash You Never See
Origination, setup, and processing fees often come out before the money lands. Borrow $50,000 with a 3% fee, and you receive $48,500. You still repay the full $50,000, and interest runs on money you never touched.
ASK THIS: Can you list every fee and when it’s charged?
3. Prepayment Rules: The Exit Toll
Paying early sounds like a win. Some contracts disagree. They add a penalty, or they still charge you the full interest. The savings you pictured never show up. Spot this one early. It’s often a single sentence near the end.
ASK THIS: If I pay this off early, what do I owe?
4. Payment Schedule: When the Money Leaves
Monthly, weekly, or daily? It matters more than most people think. Weekly payments can hit before your customers pay you. A daily pull can strain a business that gets paid monthly.
Length matters, too. Longer terms feel gentle each month, yet they cost more overall. Here’s the proof.
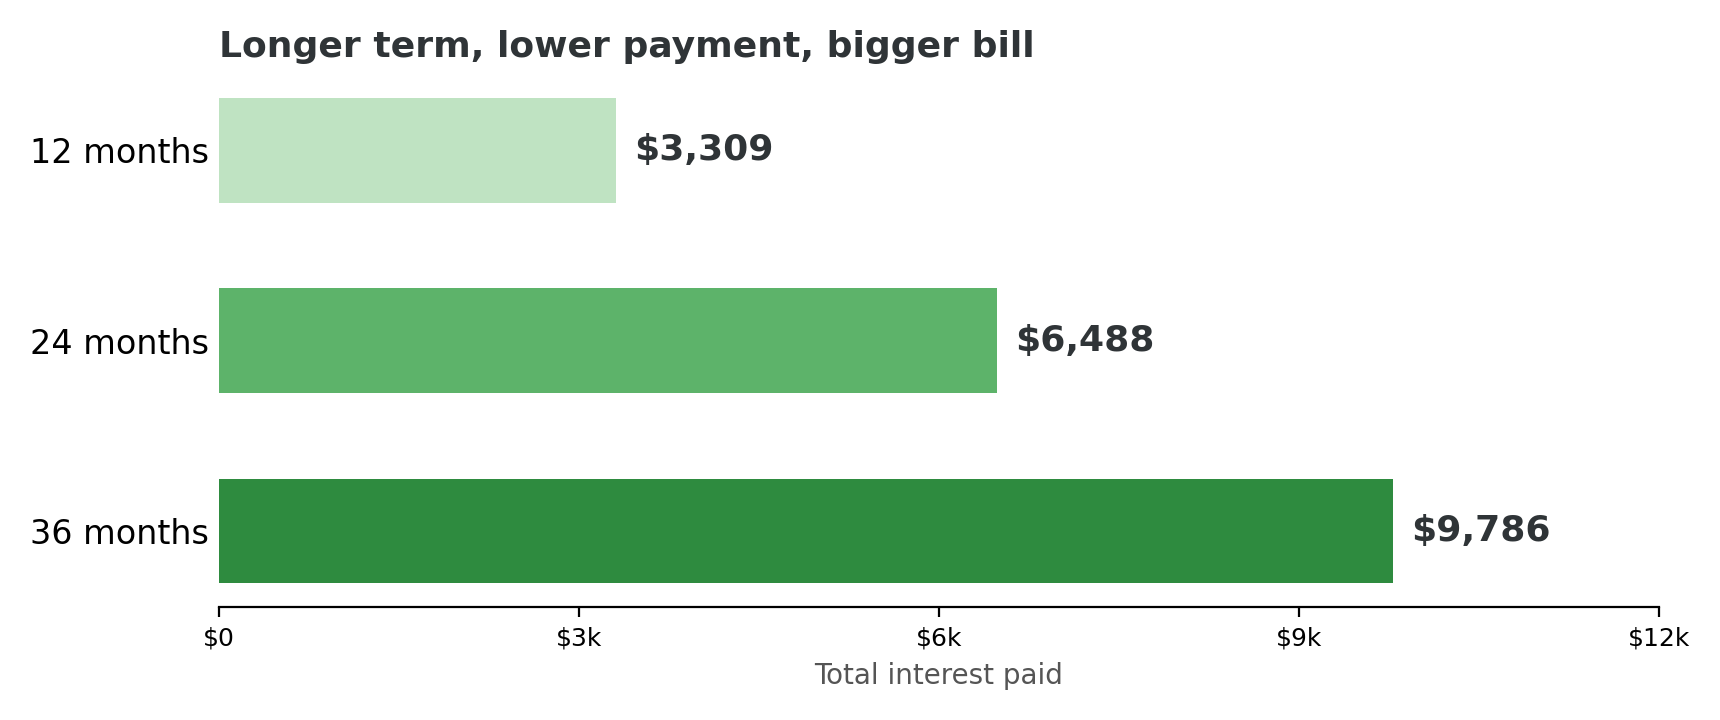
Stretching to 36 months adds about $6,500 more interest than a 12-month term.
Shorter terms save money but squeeze cash. Pick the one your cash flow can carry.
ASK THIS: Can I see the full payment schedule with dates?
5. Collateral and Guarantees: What’s on the Line
Some loans rest on the asset you buy. Others reach further. A blanket lien covers all your business assets. A personal guarantee puts your own savings in play. Know which one you’re signing. Ask what happens to that guarantee if the business closes.
ASK THIS: What backs this loan, and does it include me personally?
6. Default and Late Clauses: The Rough-Month Rules
Every owner hits a bad month. Your contract decides what happens next. Look for late fees, higher rates after a miss, and acceleration clauses that make the whole balance due at once. These clauses stay asleep until trouble hits. Then they matter most.
ASK THIS: What counts as default, and is there a grace period?
7. Balloon Payments: The Surprise Finale
Low payments can hide a monster at the end. A balloon payment is one big lump due on the last day. Can’t cover it? You may need to refinance, often with new fees. Do the math on that last payment before you sign.
ASK THIS: Does any payment grow or come due all at once?
Two Offers, Same $50,000: Spot the Winner
Picture two offers on a 12-month, $50,000 loan. Offer A looks cheaper at first glance. Look closer.
|
Detail |
Offer A |
Offer B |
|---|---|---|
|
Rate |
8% |
10% |
|
Upfront fee |
3% ($1,500) |
None |
|
Interest, 12 months |
About $2,190 |
About $2,750 |
|
Total cost |
About $3,690 |
About $2,750 |
Offer B wins by roughly $940, even with the higher rate. The loan terms did the talking, not the headline number.
Speed Isn’t a Term, But It Matters
Fast money is great. Slow money can sink a project. That’s why equipment financing approval in 24 hours turns heads, while banks often take 2 to 4 months.
But fast should never mean blind. Quick approval only wins when the loan terms are out in the open. Ask for the details in writing early. A quick yes means little if the fine print shows up after you’ve committed.
Red Flags vs. Green Flags
Some signs say loan terms deserve a second look. Here’s the quick contrast.
|
Red Flag |
Green Flag |
|---|---|
|
Quotes only a factor rate |
Shows APR and total payback |
|
Fees buried on page nine |
Fees listed up front |
|
Pressure to sign today |
Time to read and ask |
|
Vague default wording |
A clear grace period |
Your 60-Second Skim Test
Answer honestly. Yes or no:
- Do you know your APR, not just your rate?
- Can you name every fee?
- Do you know if early payoff costs extra?
- Do you know when each payment hits your account?
- Do you know what backs the loan?
Fewer than five yeses? Then you’re signing blind. The next section fixes that.
The 10-Minute Contract Check
Before you sign any set of loan terms, grab a pen and a coffee. Then run this check:
- Circle every dollar figure. Add them up.
- Hunt for fees, penalties, liens, and guarantees.
- Ask for the total payback in writing.
- Line up two offers side by side.
- Call your advisor about anything fuzzy.
- Mark any term you can’t explain in one sentence.
|
PRO TIP Ask your advisor to mark the seven terms in your contract. Seeing them highlighted takes the stress out of reading. |
Skim Less. Keep More.
Your lender reads every line. You should, too. These seven loan terms decide what you truly pay, what you risk, and how much breathing room you keep.
Read the rate. Then read past it. Ask the seven questions. Get answers in writing. Ten minutes now can save you months of regret. Read it twice. Ask twice. Sign once.
Think of the contract as a map. The rate is only the road sign. The rest shows where the road actually goes.
Don’t be the owner who finds out after the first payment.
Skip the Fine-Print Fear: Get Straight Answers from Simply Capital SourceAt Simply Capital Source, a funding advisor walks you through your options in plain English before you commit. No jargon maze. No pressure. Questions are welcome on every line. And we move fast. Equipment financing approval in 24 hours is the goal, because your business can’t wait four months for a yes. Every day you wait is a day a rival gets the gear you wanted. Get your terms straight today. Apply Today | Call (201) 357-0308 |
Frequently Asked Questions
Q1. Which loan terms matter most?
Start with APR, fees, and prepayment rules. Then check the schedule, collateral, default clauses, and balloon payments. Those seven drive your real cost.
Q2. Can I negotiate loan terms?
Often, yes. Fees, term length, and payment timing can sometimes move. Ask your advisor what’s flexible before you sign.
Q3. Is the lowest rate always the best deal?
Not always. A low rate with heavy fees can cost more than a higher rate with clean terms. Compare total payback, not just the rate.
Q4. Does fast funding mean worse terms?
No. Equipment financing approval in 24 hours can still come with clear, fair terms. Speed is a process choice, but read everything first.
Q5. What if I don’t understand a clause?
Don’t sign yet. Ask for a plain-English explanation in writing, then talk with your funding advisor or a lawyer. No question is too small.