Contact Us Now (201)-357-0308
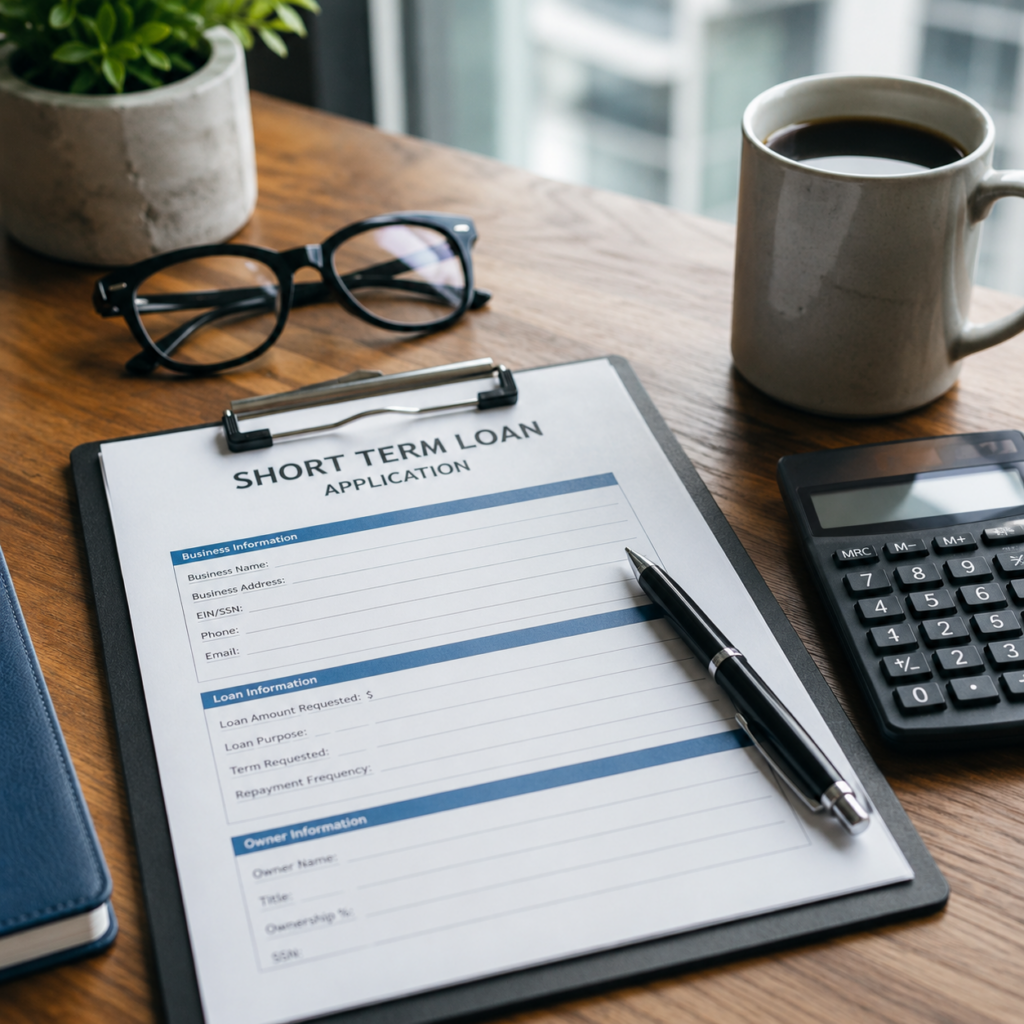
SHORT TERM LOAN
In and Out Fast. Minimal Interest. Maximum Simplicity.
Not every funding need requires years of repayment. Sometimes you just need a defined amount, for a defined purpose, paid back quickly with the least amount of interest possible.
That’s exactly what a short term loan is built for. Businesses comparing a short term vs long term business loan often choose a short-term option when speed and lower overall borrowing costs matter most.
What Is a Short Term Loan?
A short term loan is smaller, faster-repaying business financing typically repaid within 6 to 8 months. Because the repayment period is compressed, the total interest cost is lower than longer financing structures, even if the monthly payment is higher.
This product is built for business owners who care more about minimizing total cost than minimizing monthly payments.
It's commonly used for:
- A specific, short-term cash need with a clear payoff timeline
- Bridging a brief gap between a known incoming payment and a current obligation
- Covering a one-time expense without committing to years of repayment
- Businesses that want to be debt-free again quickly
If your priority is “get me what I need and let me be done with it fast,” a short term loan delivers exactly that. Understanding the difference between a short term vs long term business loan can also help you choose the financing option that best supports your cash flow.
Why a Short Term Loan Might Be Your Smartest Option
Lower total interest cost.
Compressed repayment periods mean less time for interest to accrue, helping reduce the total borrowing cost compared to longer-term financing for the same amount.
Fast approval and funding.
Short-term loans typically move quickly through underwriting, allowing many businesses to receive approval and funding within 24–48 hours of applying.
Clear, defined
payoff timeline.
There’s no years-long commitment. You know exactly when the loan will be fully repaid, making it easier to plan your finances with confidence.
Ideal for specific,
one-time needs.
When you need funding for a single project or short-term expense, this provides a simple financing solution without committing to ongoing credit.
Less concern about extended cash flow exposure.
If your business can support higher monthly payments, a shorter repayment term reduces long-term financial obligations while keeping overall borrowing costs lower.
If your need is more about manageable monthly payments than minimizing total interest, our business term loans with longer repayment periods may be the better structural fit.
Who Qualifies?
- 1 year in business
- $100,000+ in annual revenue
- 550+ FICO credit score
- Demonstrated ability to manage the compressed repayment schedule
Because repayment is fast, lenders want to see strong, consistent cash flow that can comfortably absorb the higher monthly obligation. If your credit and revenue profile is especially strong, an SBA loan could offer an even lower-cost path for larger needs.
THE PROCESS
How It Works
Step 1
Apply
Complete a quick online application by providing your business financials and the key details needed to begin the approval process.
Step 2
Review
Your advisor reviews your cash flow, financial performance, and repayment capacity to confirm the short repayment structure is fit.
Step 3
Approval
Receive a lending decision, typically within 24–48 hours, once your application and financial information have been carefully reviewed.
Step 4
Funding
Funds are deposited quickly into your account, and your repayment schedule begins with a predictable timeline and defined payoff date.
WHY SIMPLY CAPITAL SOURCE?
Short Term Funding Without the Guesswork
Short term loans look simple on the surface, but the details- total cost, payment frequency, and prepayment terms vary significantly between lenders. We make sure you understand exactly what you’re agreeing to.
Your dedicated advisor will also tell you honestly if a short term loan isn’t actually your most cost-effective option. Sometimes a different financing structure serves your specific situation better, and we’d rather guide you to the right one than recommend the wrong solution.
Because we work across a full lending network, we can compare short-term loan offers side by side rather than presenting just one option. If you’re weighing a short term vs long term business loan, we’ll help you understand the benefits of each before you make a decision.
Need Help Choosing the Right Financing Option?
Not every business has the same funding needs, which is why speaking with a small business financing consultant can save both time and money. Whether you’re comparing a short term loan, SBA loan, line of credit, or equipment financing, our advisors provide help choosing the right business loan based on your business goals, cash flow, and repayment preferences. Instead of guessing which financing product fits best, you receive expert guidance that helps you move forward with confidence.
Frequently Asked Questions (FAQs)
Advance rates vary based on invoice quality, your clients’ payment history, and your industry. Your advisor will give you a specific figure during the review process.
This depends on the structure of your specific arrangement. Some arrangements are disclosed to clients; others aren’t. Your advisor will explain the structure that applies to your deal.
This is addressed in your specific financing agreement. Your advisor will walk you through exactly how this scenario is handled before you commit.
Not exactly. It’s an advance against money you’re already owed, rather than a traditional loan against your creditworthiness. That’s why approval often depends more on your invoices and clients than your personal credit.
Both options exist depending on the lender and your needs. Some businesses use it occasionally for large invoices; others structure ongoing facilities. Ask your advisor what fits your situation and whether a line of credit might suit recurring needs better.
Then a line of credit may give you more ongoing flexibility than a one-time invoice advance. Your advisor can compare both based on your revenue pattern.